Monthly financial checklist: 12 things every business owner should review
Use this monthly financial checklist to review cash, bills, cards, withdrawals, indicators, and commitments before making decisions.
A monthly financial checklist should include at least twelve checks: reconciled balances, income, expenses, payables and receivables, statements, future installments, taxes, owner salaries, withdrawals, reserves, indicators, and an action plan for the next month.
For doctors, lawyers, business owners, and independent professionals, month-end is the time to turn scattered transactions into a clear picture. The aim is not a polished report, but answers to practical questions: how much the business really generated, how much can be withdrawn, which commitments already exist, and where a cash shortage is possible.
Why close your finances every month?
Without regular reviews, the bank balance tends to become the main basis for decisions. But it only shows the money available at that moment. It does not show unpaid expenses, future installments, taxes, overdue receivables, or money mixed between personal and business accounts.
Sebrae describes cash flow as a tool for tracking money in and out and supporting decisions. A monthly close extends that view: it consolidates the recent past and prepares you for the next period.
A monthly financial checklist in 12 steps
1. Reconcile account balances
Compare the balances in your system with bank statements and check that every transaction was recorded. Small differences may hide fees, transfers, reversals, or expenses recorded in the wrong account.
- Confirm the balance of each personal and business account.
- Identify transfers that still need classification.
- Review duplicate or missing entries.
2. Check all income for the period
Separate invoiced sales, payments actually received, and outstanding income. A completed sale does not necessarily mean cash is available.
3. Review fixed and variable expenses
Look at which costs repeat, which have increased, and which brought no clear return. The goal is not to cut everything, but to understand operating costs and catch deviations before they become permanent.
4. Update bills to pay
List overdue bills, upcoming due dates, and recurring payments. Mark paid items and check for penalties, interest, or duplicate charges.
5. Update receivables
Organize expected payments by customer, date, and likelihood. Late payments need action; future payments need to be included in your cash forecast.
6. Analyze cards and statements
Check credit used, the current bill, installment purchases, and projected future bills. Future commitments can limit your options even when your current balance looks comfortable.
7. Set aside taxes and other obligations
Reserve the amounts needed for taxes, payroll, suppliers, and other obligations. Avoid treating this money as available for investment or withdrawals.
8. Record owner salaries, withdrawals, and reimbursements
Every transaction between an owner and the business needs context. Record salaries, distributions, contributions, reimbursements, and personal expenses paid by the company. This classification reduces confusion between personal and business finances.
9. Review reserves and goals
Check whether the business maintained or increased its safety reserve. Compare savings with fixed commitments and your stated goals.
10. Compare actuals with the plan
Identify where results were above or below expectations. The gap between the plan and reality reveals incorrect assumptions, seasonality, or changes to include in the next budget.
11. Track a few relevant indicators
Choose indicators that support business decisions, such as projected balance, operating margin, average collection period, fixed expenses, and credit utilization. Numbers that do not lead to action just add noise.
12. Set three actions for next month
Finish the close with specific decisions. Examples include following up on overdue invoices, renegotiating an expense, reducing business card purchases, or increasing reserves.
A monthly summary for the business owner
A useful summary fits on one screen and explains the situation without requiring advanced accounting knowledge.
- Current balance and projected balance at the end of next month.
- Total received, total paid, and the financial result for the period.
- Overdue bills and commitments for the next 30 days.
- Current statements and existing installment commitments.
- Amounts between owner and company that require reimbursement or offsetting.
- Three priority decisions.
How Vinica helps with the monthly close
Vinica brings together transactions, accounts, cards, documents, commitments, and transfers between personal and business finances. Text, voice notes, photos, and files sent through WhatsApp can be organized on the dashboard, reducing the work of reconstructing the month on its final day.
Subscribe to Vinica: CLICK HERE
Frequently asked questions
When should I close my finances?
Ideally, review operations throughout the month and complete a formal close in the first few days of the next period. The information is still fresh, and there is time to adjust your plans.
Do I need an accountant for this review?
An accountant is essential for accounting and tax obligations. Business owners should also understand the management checklist so it can support everyday decisions.
Can I close the month just by looking at my bank statement?
This is not recommended. A statement does not show future commitments, receivables, correct expense categories, or the impact of existing installments.
Summary: Review balances, income, expenses, accounts, cards, taxes, personal and business transfers, reserves, and indicators. Finish with clear actions for next month.
Sources and references
We help people managing a business, a family, and a busy life organize everything with greater clarity.
Browse categories
Newsletter
Organize better today. Make clearer decisions tomorrow.
Get practical advice on financial management, cash flow, cards, personal and business finances, AI, and productivity for people managing both a business and a personal life.
USE CODE: BLOGVINICA
Copied
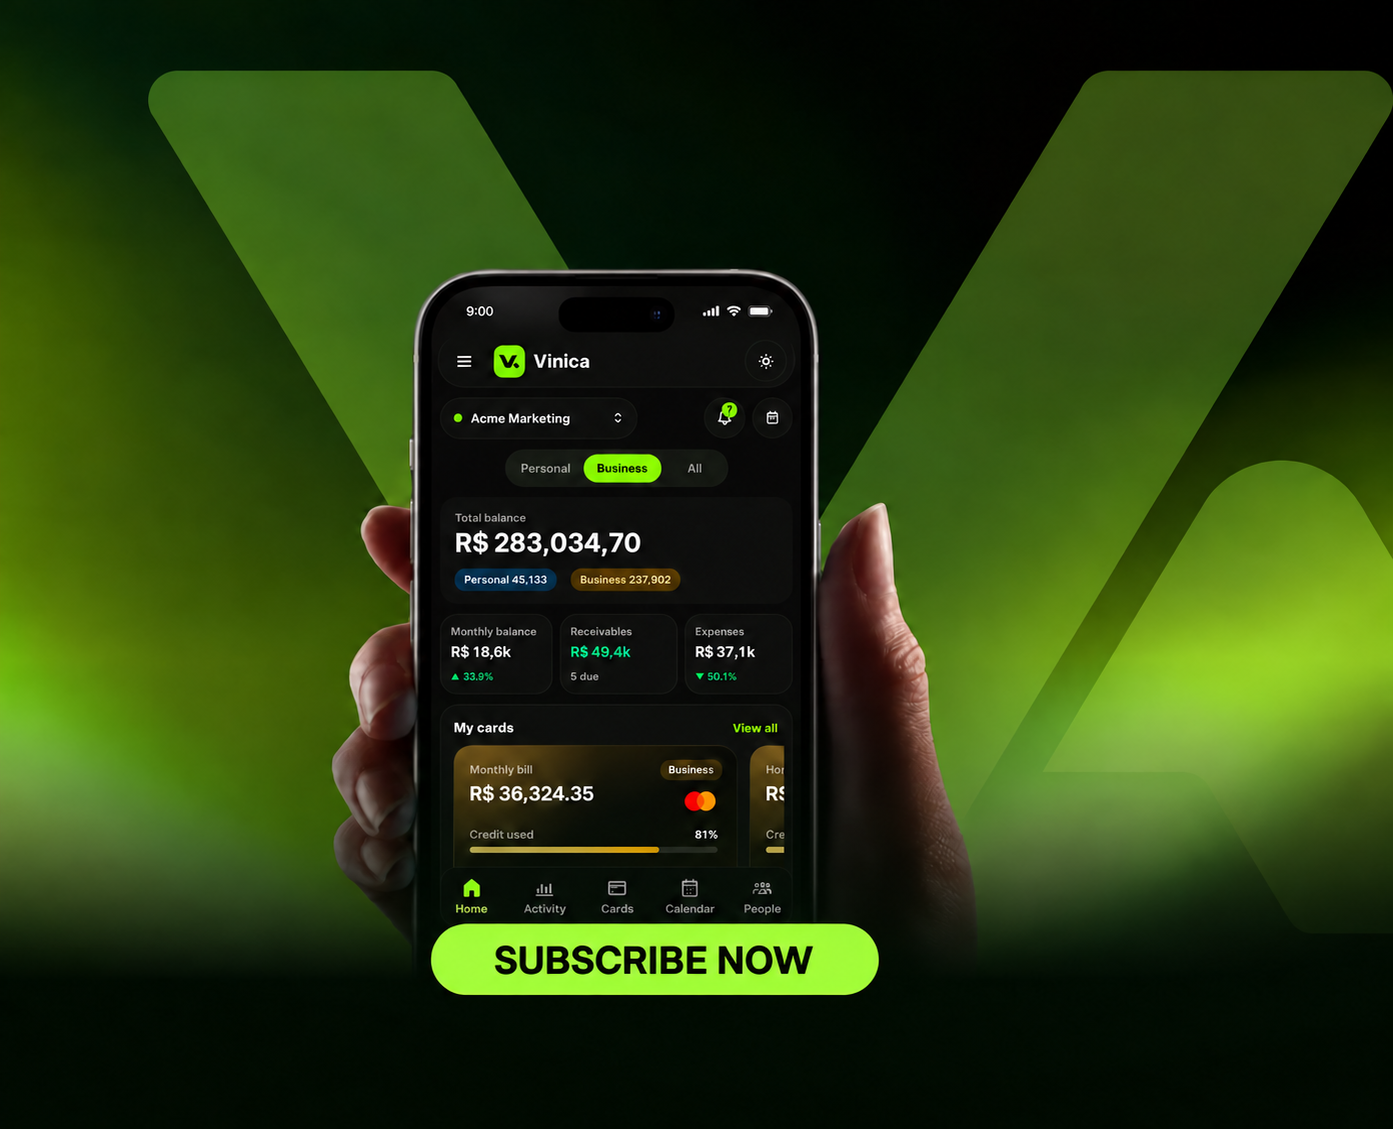
Organize your business and personal life for 33% less.
Get the complete Vinica to manage finances, cards, accounts, documents, and appointments with AI on WhatsApp.
Subscribe to Vinica and organize all your finances today.
Record it on WhatsApp. Track it on your dashboard. Organize your business, family, documents, and daily life with an assistant that sees the whole picture.